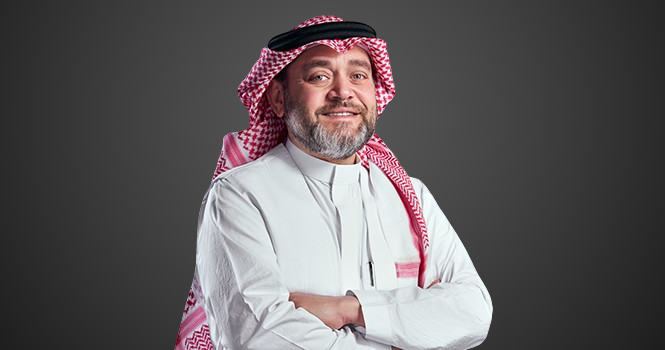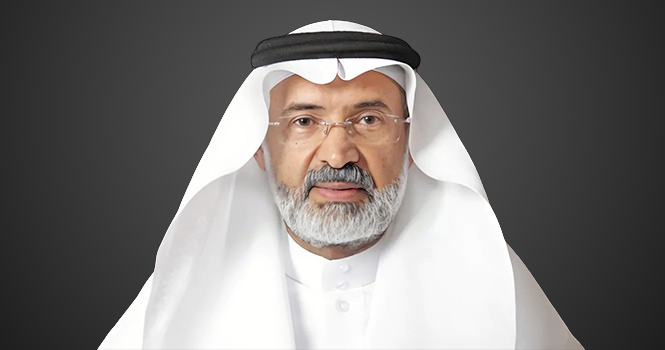
Shoeil Al Ayed, CEO of Riyadh Cement Co.
The company is monitoring market developments and demand levels, while working to boost operational efficiency and maintain its competitiveness, said the top executive. He expects a relative improvement in demand and selling prices during Q4 2026, as regional conditions stabilize and market activity improves. 
Regarding the company’s Q3 2026 results, Al Ayed explained that the 73% YoY increase in profit to around SAR 26 million was mainly driven by revenue growth to approximately SAR 168.7 million, driven by higher sales volumes and selling prices of black cement.
He added that the gross profit margin increased from 20% to around 24.5%, supported by improved operating performance and production cost management, as well as lower general and administrative expenses and selling and marketing expenses.
Commenting on sales, Al Ayed said black cement sales reached around 838,000 tons in Q3 2026, up 5% YoY and 4% QoQ.
He noted that the average selling price of black cement reached around SAR 150 per ton, up 10% compared with Q3 2025, but down 15% from the previous quarter.
The company continues to strengthen its position in the white cement segment and capitalize on opportunities in domestic and international markets.
Al Ayed explained that production costs were affected by a 5%–6% increase in fuel prices, while the impact on the company’s profit was limited to around 2%, thanks to initiatives and projects implemented to mitigate the effect of higher fuel costs on production costs, as well as the benefit from the average cost of black and white clinker inventories.
He added that Riyadh Cement continues to implement initiatives to improve fuel consumption and operational efficiency. It has completed several projects in this area, while additional initiatives are underway to enhance production efficiency and reduce costs.
The CEO also noted that the project to switch to natural gas is one of the company’s key strategic initiatives, as it is expected to generate fuel cost savings compared with liquid fuels, supporting operating efficiency and strengthening competitiveness over the medium and long term.
He indicated that profitability margins in the coming period will remain linked to selling price developments and demand levels, alongside the company’s continued efforts to improve operational efficiency and control fuel, raw material and transportation costs.
As regards exports, Al Ayed said they are not currently a major focus of the company’s sales strategy, as it prioritizes meeting domestic market demand while maintaining selling prices and profit margins for its products.
He added that the company evaluates export opportunities based on commercial and operational considerations to ensure the best economic returns without adversely affecting the profitability of domestic sales.
Riyadh Cement continues to focus on improving its production efficiency, controlling costs and strengthening product competitiveness, while gradually transitioning toward a more automated and intelligent operating model, according to the top executive.
Al Ayed also said the company expects relative improvement in its financial performance in Q4 2026, backed by positive expectations for stronger demand and selling prices, alongside expectations of regional stability.
“We will continue to focus on improving operational efficiency, enhancing production cost management and benefiting from ongoing development initiatives and projects, supporting profit margins and the sustainability of our financial and operational performance,” he added.
According to Argaam data, Riyadh Cement’s profit declined to SAR 136 million in 9M 2026, compared with SAR 148 million in the same period last year. Q3 2026 net profit rose 73% YoY to SAR 26 million.
Shoeil Al Ayed, CEO of Riyadh Cement Co.
The company is monitoring market developments and demand levels, while working to boost operational efficiency and maintain its competitiveness, said the top executive. He expects a relative improvement in demand and selling prices during Q4 2026, as regional conditions stabilize and market activity improves.
Regarding the company’s Q3 2026 results, Al Ayed explained that the 73% YoY increase in profit to around SAR 26 million was mainly driven by revenue growth to approximately SAR 168.7 million, driven by higher sales volumes and selling prices of black cement.
He added that the gross profit margin increased from 20% to around 24.5%, supported by improved operating performance and production cost management, as well as lower general and administrative expenses and selling and marketing expenses.
Commenting on sales, Al Ayed said black cement sales reached around 838,000 tons in Q3 2026, up 5% YoY and 4% QoQ.
He noted that the average selling price of black cement reached around SAR 150 per ton, up 10% compared with Q3 2025, but down 15% from the previous quarter.
The company continues to strengthen its position in the white cement segment and capitalize on opportunities in domestic and international markets.
Al Ayed explained that production costs were affected by a 5%–6% increase in fuel prices, while the impact on the company’s profit was limited to around 2%, thanks to initiatives and projects implemented to mitigate the effect of higher fuel costs on production costs, as well as the benefit from the average cost of black and white clinker inventories.
He added that Riyadh Cement continues to implement initiatives to improve fuel consumption and operational efficiency. It has completed several projects in this area, while additional initiatives are underway to enhance production efficiency and reduce costs.
The CEO also noted that the project to switch to natural gas is one of the company’s key strategic initiatives, as it is expected to generate fuel cost savings compared with liquid fuels, supporting operating efficiency and strengthening competitiveness over the medium and long term.
He indicated that profitability margins in the coming period will remain linked to selling price developments and demand levels, alongside the company’s continued efforts to improve operational efficiency and control fuel, raw material and transportation costs.
As regards exports, Al Ayed said they are not currently a major focus of the company’s sales strategy, as it prioritizes meeting domestic market demand while maintaining selling prices and profit margins for its products.
He added that the company evaluates export opportunities based on commercial and operational considerations to ensure the best economic returns without adversely affecting the profitability of domestic sales.
Riyadh Cement continues to focus on improving its production efficiency, controlling costs and strengthening product competitiveness, while gradually transitioning toward a more automated and intelligent operating model, according to the top executive.
Al Ayed also said the company expects relative improvement in its financial performance in Q4 2026, backed by positive expectations for stronger demand and selling prices, alongside expectations of regional stability.
“We will continue to focus on improving operational efficiency, enhancing production cost management and benefiting from ongoing development initiatives and projects, supporting profit margins and the sustainability of our financial and operational performance,” he added.
According to Argaam data, Riyadh Cement’s profit declined to SAR 136 million in 9M 2026, compared with SAR 148 million in the same period last year. Q3 2026 net profit rose 73% YoY to SAR 26 million.