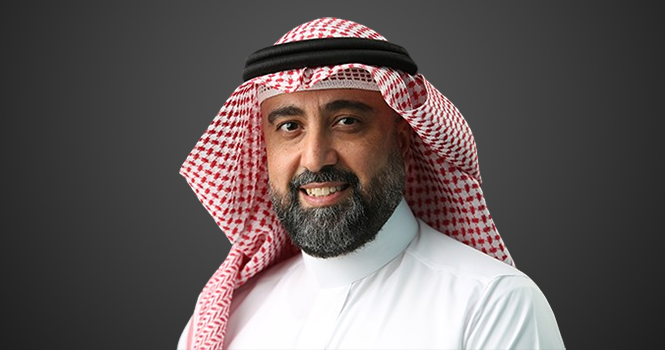
Ala’ Al-Shaikh, CEO ofBasic Chemical Industries Co. (BCI)
Basic Chemical Industries Co. (BCI) expects its performance in Q4 2026 to remain at levels similar to those recorded in Q2 and Q3, despite some pressure on profit margins from higher raw material and import costs, as well as competition, CEO Ala’ Al-Shaikh told Argaam. 
Al-Shaikh said the company’s improved Q3 earnings were driven by sales growth, better margins, and cost efficiency. Revenue rose 12.9% to approximately SAR 215 million, while cost of sales increased 10.5%, lifting gross profit by 21.3% to SAR 51.3 million. The gross profit margin also improved to 23.9% from 22.2% in the year-earlier period.
The group’s operating profit increased 26.8% to approximately SAR 28.5 million, with the operating margin improving to 13.2% from 11.8%. Lower financing costs, which declined to SAR 3.8 million from approximately SAR 5 million, also supported net profit.
The group’s total net profit reached SAR 23.6 million, of which SAR 15.48 million was attributable to the company’s shareholders, compared with SAR 9.8 million in Q3 2025, representing growth of approximately 58%.
Polymers emerge as key driver of profitability growth
Al-Shaikh said the polymers segment delivered the strongest growth in earnings and margins in Q3, with sales increasing by approximately 28%.
The segment’s gross profit rose to SAR 13.7 million from SAR 7 million, while operating profit increased to SAR 12 million from SAR 5.3 million. Gross profit margin reached approximately 31.1%.
In the adhesives segment, sales increased to SAR 69.9 million from SAR 65.2 million. Gross profit reached SAR 15.4 million, while operating profit declined to SAR 7.2 million from SAR 8.1 million, indicating that sales growth did not fully translate into higher operating profitability during the quarter.
Sales in the chemicals segment reached approximately SAR 101 million, generating gross profit of SAR 22.2 million and operating profit of SAR 9.25 million. Basic chemicals accounted for SAR 79.7 million in sales and SAR 18.6 million in gross profit.
Al-Shaikh also highlighted strong growth in the water treatment business, where sales increased to SAR 7.8 million from approximately SAR 4.5 million, while operating profit rose to SAR 1.6 million from around SAR 500,000 in the year-earlier quarter.
He noted that profit margins vary across the group’s segments due to differences in product and market characteristics. Polymers was the main driver of improved profitability in Q3, while basic chemicals maintained its significant contribution to business volume and water treatment recorded strong growth from a smaller base.
Higher transportation and inventory costs
Regarding cost developments, Al-Shaikh said inventory and material costs increased 3.8% in the first nine months of 2026, while transportation costs rose 8.8%, alongside higher depreciation expenses. He also noted that the year included some non-recurring accounting adjustments, adding that the company remains focused on underlying operating trends, unit cost management, and product margins.
He indicated regional geopolitical tensions had put some pressure on transportation and logistics services. Transportation costs included in cost of sales increased to SAR 26.3 million in the first nine months, compared with SAR 24.1 million in the same period last year. Distribution expenses also rose to SAR 13.6 million from SAR 11.8 million.
The group increased its inventory to approximately SAR 159.2 million as of end-September 2026, compared with SAR 108.3 million at year-end 2025, marking an increase of around 47%. This included an increase of approximately SAR 43 million in the adhesives unit’s inventory and around SAR 8 million in the polymers unit’s inventory.
He explained that the increase was aimed at enhancing the company’s flexibility in managing supply chain fluctuations and rising costs. The company is proactively managing inventory and suppliers while optimizing its product mix, operational efficiency, and pricing policies to absorb cost fluctuations as much as possible.
Energy costs and operational efficiency
On electricity and water costs, Al-Shaikh said the company continues to monitor energy and utility expenses, adding that their impact remained under control through the end of Q3. Energy costs increased 1.4% to SAR 20.9 million in the first nine months, compared with SAR 20.6 million in the year-earlier period.
He added that the company continues to improve asset and production efficiency and reduce unit costs to help maintain operating margins amid higher costs for some raw materials and imports, as well as competitive pressures.
Ala’ Al-Shaikh, CEO ofBasic Chemical Industries Co. (BCI)
Basic Chemical Industries Co. (BCI) expects its performance in Q4 2026 to remain at levels similar to those recorded in Q2 and Q3, despite some pressure on profit margins from higher raw material and import costs, as well as competition, CEO Ala’ Al-Shaikh told Argaam.
Al-Shaikh said the company’s improved Q3 earnings were driven by sales growth, better margins, and cost efficiency. Revenue rose 12.9% to approximately SAR 215 million, while cost of sales increased 10.5%, lifting gross profit by 21.3% to SAR 51.3 million. The gross profit margin also improved to 23.9% from 22.2% in the year-earlier period.
The group’s operating profit increased 26.8% to approximately SAR 28.5 million, with the operating margin improving to 13.2% from 11.8%. Lower financing costs, which declined to SAR 3.8 million from approximately SAR 5 million, also supported net profit.
The group’s total net profit reached SAR 23.6 million, of which SAR 15.48 million was attributable to the company’s shareholders, compared with SAR 9.8 million in Q3 2025, representing growth of approximately 58%.
Polymers emerge as key driver of profitability growth
Al-Shaikh said the polymers segment delivered the strongest growth in earnings and margins in Q3, with sales increasing by approximately 28%.
The segment’s gross profit rose to SAR 13.7 million from SAR 7 million, while operating profit increased to SAR 12 million from SAR 5.3 million. Gross profit margin reached approximately 31.1%.
In the adhesives segment, sales increased to SAR 69.9 million from SAR 65.2 million. Gross profit reached SAR 15.4 million, while operating profit declined to SAR 7.2 million from SAR 8.1 million, indicating that sales growth did not fully translate into higher operating profitability during the quarter.
Sales in the chemicals segment reached approximately SAR 101 million, generating gross profit of SAR 22.2 million and operating profit of SAR 9.25 million. Basic chemicals accounted for SAR 79.7 million in sales and SAR 18.6 million in gross profit.
Al-Shaikh also highlighted strong growth in the water treatment business, where sales increased to SAR 7.8 million from approximately SAR 4.5 million, while operating profit rose to SAR 1.6 million from around SAR 500,000 in the year-earlier quarter.
He noted that profit margins vary across the group’s segments due to differences in product and market characteristics. Polymers was the main driver of improved profitability in Q3, while basic chemicals maintained its significant contribution to business volume and water treatment recorded strong growth from a smaller base.
Higher transportation and inventory costs
Regarding cost developments, Al-Shaikh said inventory and material costs increased 3.8% in the first nine months of 2026, while transportation costs rose 8.8%, alongside higher depreciation expenses. He also noted that the year included some non-recurring accounting adjustments, adding that the company remains focused on underlying operating trends, unit cost management, and product margins.
He indicated regional geopolitical tensions had put some pressure on transportation and logistics services. Transportation costs included in cost of sales increased to SAR 26.3 million in the first nine months, compared with SAR 24.1 million in the same period last year. Distribution expenses also rose to SAR 13.6 million from SAR 11.8 million.
The group increased its inventory to approximately SAR 159.2 million as of end-September 2026, compared with SAR 108.3 million at year-end 2025, marking an increase of around 47%. This included an increase of approximately SAR 43 million in the adhesives unit’s inventory and around SAR 8 million in the polymers unit’s inventory.
He explained that the increase was aimed at enhancing the company’s flexibility in managing supply chain fluctuations and rising costs. The company is proactively managing inventory and suppliers while optimizing its product mix, operational efficiency, and pricing policies to absorb cost fluctuations as much as possible.
Energy costs and operational efficiency
On electricity and water costs, Al-Shaikh said the company continues to monitor energy and utility expenses, adding that their impact remained under control through the end of Q3. Energy costs increased 1.4% to SAR 20.9 million in the first nine months, compared with SAR 20.6 million in the year-earlier period.
He added that the company continues to improve asset and production efficiency and reduce unit costs to help maintain operating margins amid higher costs for some raw materials and imports, as well as competitive pressures.