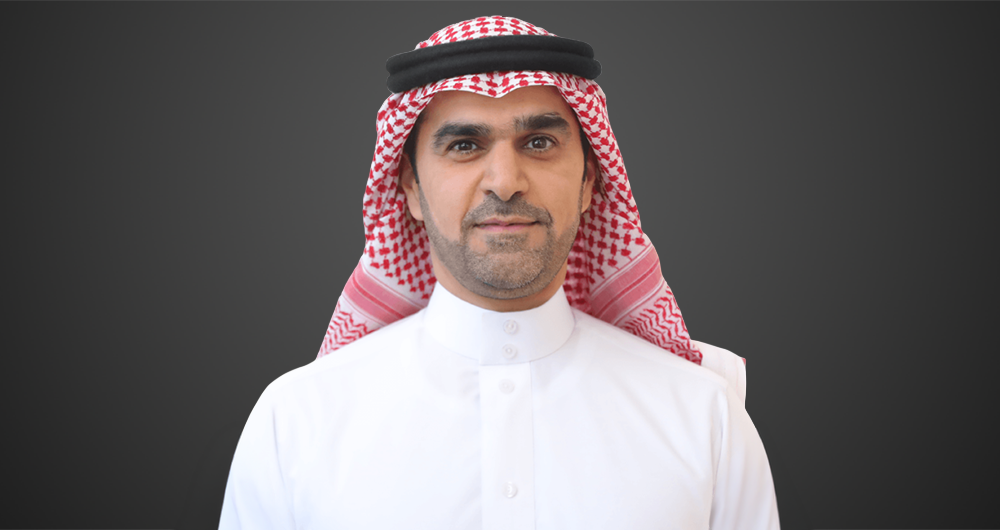
Abdulaziz Al-Oud,CFO ofSaudi Pharmaceutical Industries and Medical Appliances Corp.’s (SPIMACO)
Saudi Pharmaceutical Industries and Medical Appliances Corp.’s (SPIMACO) swinging to a loss in Q3 2026 was driven by lower sales to the government sector and higher expected credit loss provisions due to slower collections from some customers, CFO Abdulaziz Al-Oud told Argaam. 
The company continued to make progress in revenue quality and margins. However, the impact of lower government sales and higher provisions outweighed the benefits of operational improvements, weighing on the bottom line, according to the official.
He added that operating expenses increased at a faster pace than revenue growth, limiting the extent to which the improvement in gross profit translated into higher net earnings.
The results were also affected by SAR 19 million in impairment provisions for financial assets, in addition to a non-recurring expense of SAR 24 million resulting from the reversal of a deferred tax asset following a reassessment of the tax treatment associated with a change in the ownership structure, said the CFO.
Impairment provisions for financial assets amounted to SAR 29 million in the first nine months of 2026, mainly related to receivables and a review of the associated credit risks, he added.
Al-Oud further stated that SPIMACO adopts a conservative approach to assessing collection risks, while continuing to monitor receivables, strengthen collection procedures, and manage working capital.
He indicated that cash flow from operating activities fell by around 64% to SAR 69 million in the first nine months of 2026, from SAR 190 million a year earlier.
Moreover, improving cash generation is a key management priority. The company is focused on improving its collection cycle, strengthening expense management discipline, and enhancing the efficiency of inventory and receivables. These measures are intended to support liquidity and the company’s ability to finance its operations and strategic priorities, according to Al-Oud.
On the decline in the private sector’s contribution from 67% to 58% of the company’s total sales, Al-Oud explained that this change does not necessarily reflect customer losses or a structural decline in the company’s market position. Rather, it resulted from more challenging market conditions and intensifying competition, as well as decisions taken by the company to preserve profitability and avoid expanding sales that do not generate the required commercial returns.
He affirmed that the private sector remains a key component of the company’s business, adding that SPIMACO is focused on strengthening customer relationships, improving commercial execution, and directing investments toward priority brands and therapeutic categories.
“We are also working to restore profitable growth in this channel while maintaining revenue quality and margins, rather than increasing sales volumes at the expense of financial sustainability,” he added.
Regarding the outlook for Q4 2026, Al-Oud said the company is focusing on building commercial momentum, improving operational efficiency, and bolstering working capital management to strengthen its ability to convert revenue into sustainable earnings and cash flows.
He added that SPIMACO continues to develop its product portfolio through partnerships and investments in specialty medicines, biologics, vaccines, and oncology treatments, while also strengthening the performance of its core businesses to support long-term growth.
These initiatives take into account development requirements, regulatory approvals, manufacturing readiness, and market access, he continued.
Al-Oud also emphasized that the company does not provide detailed financial forecasts for upcoming periods except through its official disclosures and approved channels. He highlighted that the management remains focused on improving revenue growth, enhancing operating leverage, strengthening cash flows, and building a more sustainable foundation for long-term shareholder value creation.
According to Argaam’s data, SPIMACO reported a net profit of SAR 100.2 million for the first nine months of 2026, compared to SAR 145.6 million in the same period a year earlier. Q3 net loss amounted to nearly SAR 33.3 million.
Abdulaziz Al-Oud,CFO ofSaudi Pharmaceutical Industries and Medical Appliances Corp.’s (SPIMACO)
Saudi Pharmaceutical Industries and Medical Appliances Corp.’s (SPIMACO) swinging to a loss in Q3 2026 was driven by lower sales to the government sector and higher expected credit loss provisions due to slower collections from some customers, CFO Abdulaziz Al-Oud told Argaam.
The company continued to make progress in revenue quality and margins. However, the impact of lower government sales and higher provisions outweighed the benefits of operational improvements, weighing on the bottom line, according to the official.
He added that operating expenses increased at a faster pace than revenue growth, limiting the extent to which the improvement in gross profit translated into higher net earnings.
The results were also affected by SAR 19 million in impairment provisions for financial assets, in addition to a non-recurring expense of SAR 24 million resulting from the reversal of a deferred tax asset following a reassessment of the tax treatment associated with a change in the ownership structure, said the CFO.
Impairment provisions for financial assets amounted to SAR 29 million in the first nine months of 2026, mainly related to receivables and a review of the associated credit risks, he added.
Al-Oud further stated that SPIMACO adopts a conservative approach to assessing collection risks, while continuing to monitor receivables, strengthen collection procedures, and manage working capital.
He indicated that cash flow from operating activities fell by around 64% to SAR 69 million in the first nine months of 2026, from SAR 190 million a year earlier.
Moreover, improving cash generation is a key management priority. The company is focused on improving its collection cycle, strengthening expense management discipline, and enhancing the efficiency of inventory and receivables. These measures are intended to support liquidity and the company’s ability to finance its operations and strategic priorities, according to Al-Oud.
On the decline in the private sector’s contribution from 67% to 58% of the company’s total sales, Al-Oud explained that this change does not necessarily reflect customer losses or a structural decline in the company’s market position. Rather, it resulted from more challenging market conditions and intensifying competition, as well as decisions taken by the company to preserve profitability and avoid expanding sales that do not generate the required commercial returns.
He affirmed that the private sector remains a key component of the company’s business, adding that SPIMACO is focused on strengthening customer relationships, improving commercial execution, and directing investments toward priority brands and therapeutic categories.
“We are also working to restore profitable growth in this channel while maintaining revenue quality and margins, rather than increasing sales volumes at the expense of financial sustainability,” he added.
Regarding the outlook for Q4 2026, Al-Oud said the company is focusing on building commercial momentum, improving operational efficiency, and bolstering working capital management to strengthen its ability to convert revenue into sustainable earnings and cash flows.
He added that SPIMACO continues to develop its product portfolio through partnerships and investments in specialty medicines, biologics, vaccines, and oncology treatments, while also strengthening the performance of its core businesses to support long-term growth.
These initiatives take into account development requirements, regulatory approvals, manufacturing readiness, and market access, he continued.
Al-Oud also emphasized that the company does not provide detailed financial forecasts for upcoming periods except through its official disclosures and approved channels. He highlighted that the management remains focused on improving revenue growth, enhancing operating leverage, strengthening cash flows, and building a more sustainable foundation for long-term shareholder value creation.
According to Argaam’s data, SPIMACO reported a net profit of SAR 100.2 million for the first nine months of 2026, compared to SAR 145.6 million in the same period a year earlier. Q3 net loss amounted to nearly SAR 33.3 million.