✍️Islam Zween
If diesel prices rise faster than crude oil, who captures the difference? The answer seems obvious: the refineries that buy crude and turn it into higher-value fuel. But the same crisis that widens the product margin can make reaching its buyers more costly and more difficult. So how much of the gain survives the journey? 
Aramco produces crude and owns refineries in the Kingdom and abroad, so it can benefit at more than one point in the value chain. Adjusted earnings before interest and tax for its refining and chemicals business nearly doubled in the second quarter compared with the same period last year.
That is a significant improvement, but it raises a question: how much did prices contribute, and how much came from the ability to keep operating and supplying customers?
A refinery does not turn every barrel of crude into diesel. It produces a basket that includes petrol, naphtha, jet fuel and fuel oil, each with its own price and market. Margins also depend on volumes the refinery can process, crude that can reach it, and products that can be sold and shipped.
Petro Rabigh shows why these elements must be read together. Its swing from loss to profit came against a quarter that included a maintenance shutdown of around 60 days, while the roughly 69% rise in its operating profit over the previous quarter also points to a genuine improvement.
The year-on-year comparison carries the effect of the plant returning to operation; the quarter-on-quarter comparison helps us read the improvement in performance. Neither is enough to isolate the gains from diesel alone.
This links refining gains to the value of the assets that allow those gains to continue when supplies are disrupted. A high margin is of little use if crude cannot arrive or products cannot be delivered.
What took me to a broader question, though, were Amin Nasser’s remarks in London and then Riyadh about expanding storage outside the Kingdom and studying additional routes for crude exports.
Inventory that has already reached beyond a disrupted route can keep serving customers through a short outage. That capability has a cost today, while its return may show up later in sales that are not lost.
Here lies the paradox: we can see the cost of the tanks, the inventory and the extra routes, but we cannot easily see the loss that might have occurred without them. These assets may support operations and the routing of sales in normal times, then grow in value when the usual route is disrupted.
We often measure efficiency by cutting inventory, raising asset utilisation and lowering costs. These are sensible goals. But relying on a single route may lower everyday costs while raising the cost of a potential disruption.
Assessing an investment therefore requires calculating what happens when the system stops, as well as what it delivers when it works. At the same time, describing spending as a boost to resilience is not enough to justify it.
The number of alternatives alone tells us nothing about the quality of the protection. We might add storage tanks without securing a way to refill them, or diversify export outlets while they remain exposed to the same source of disruption.
The practical questions are these. How likely is a disruption, how long might it last, and what loss could it cause? How many days of supply does the inventory protect, and can it be refilled if the disruption drags on?
Is the alternative route truly independent of the risks facing the original one? Only with this comparison can we estimate what the spending protects, and judge whether its cost is proportionate to the protection it provides.
There is another calculation that goes beyond the company. Continued supplies of fuel and industrial inputs protect transport, manufacturing and essential services. The economic benefit of avoiding a disruption may therefore exceed the return that appears in Aramco’s accounts alone.
That makes it essential to distinguish between the company’s return and the value of energy security when assessing an investment and deciding who should bear its cost.
For investors, these capabilities deserve scrutiny, but they do not automatically earn the company a higher valuation. What matters is how far they protect cash flows, and what the company pays for that protection.
For policymakers, the task is to estimate the impact of a disruption on the economy, then weigh the ways of limiting it. Seen from this angle, Aramco’s results become a starting point for a broader reading.
Higher prices made gains possible, but keeping them depends on decisions about operations, transport and storage, some of them taken years before the crisis. Judging those decisions on one quarter’s profits may hide their value, just as it may hide their long-term cost.
When we assess an investment in additional storage or an alternative route, do we compare its cost only with the return from using it, or do we also count the loss it could prevent?
Aramco’s Barrel Has Two Prices
Click here to read the full study
You Read It Here First in Argaam Weekend
Aramco’s Barrel Has Two Prices
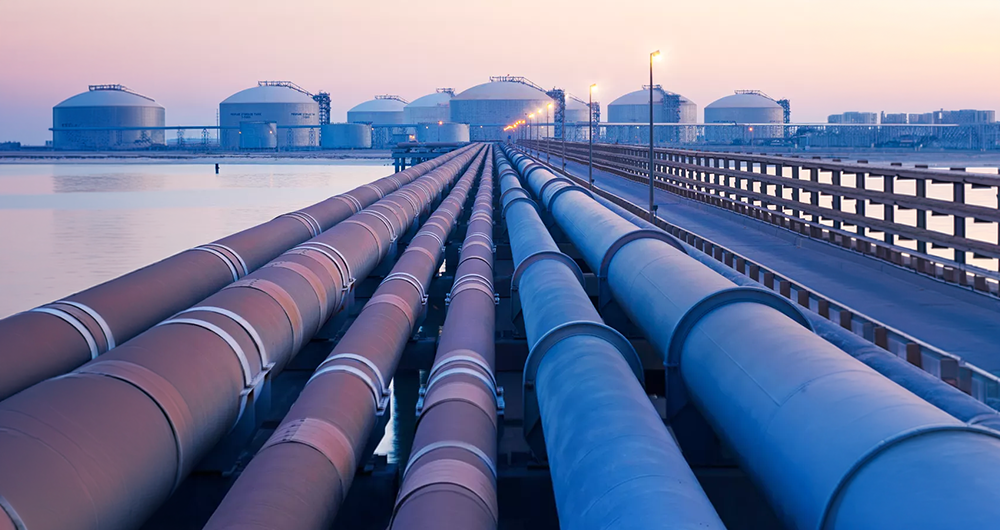
Until 10 September, the East-West Pipeline was flowing at full capacity — a strategic artery carrying 7 million barrels per day from the Eastern Province to the Red Sea to bypass the Strait of Hormuz.
When Fewer Barrels Mean More Revenue
Ask most observers what a disruption to Saudi oil exports should do to the budget, and the answer comes quickly: fewer barrels, less revenue, a wider deficit.
As Saudi Arabia ramped up refined product exports, chiefly jet fuel, through its Red Sea port of Yanbu in March 2026 due to the effective closure of the Strait of Hormuz, flows surged to near-record levels — with the pipeline feeding Yanbu running at full capacity.
Saudi Oil Through Alternative Routes: An Objective Assessment of Cost and Return
The East-West Pipeline and Yanbu terminal resolve the logistics question. What they do not resolve is the fiscal one. Even with full rerouting capacity operational, Saudi Arabia faces a gap between the price its crude commands under normal conditions and the price a disrupted.
✍️Islam Zween
If diesel prices rise faster than crude oil, who captures the difference? The answer seems obvious: the refineries that buy crude and turn it into higher-value fuel. But the same crisis that widens the product margin can make reaching its buyers more costly and more difficult. So how much of the gain survives the journey?
Aramco produces crude and owns refineries in the Kingdom and abroad, so it can benefit at more than one point in the value chain. Adjusted earnings before interest and tax for its refining and chemicals business nearly doubled in the second quarter compared with the same period last year.
That is a significant improvement, but it raises a question: how much did prices contribute, and how much came from the ability to keep operating and supplying customers?
A refinery does not turn every barrel of crude into diesel. It produces a basket that includes petrol, naphtha, jet fuel and fuel oil, each with its own price and market. Margins also depend on volumes the refinery can process, crude that can reach it, and products that can be sold and shipped.
Petro Rabigh shows why these elements must be read together. Its swing from loss to profit came against a quarter that included a maintenance shutdown of around 60 days, while the roughly 69% rise in its operating profit over the previous quarter also points to a genuine improvement.
The year-on-year comparison carries the effect of the plant returning to operation; the quarter-on-quarter comparison helps us read the improvement in performance. Neither is enough to isolate the gains from diesel alone.
This links refining gains to the value of the assets that allow those gains to continue when supplies are disrupted. A high margin is of little use if crude cannot arrive or products cannot be delivered.
What took me to a broader question, though, were Amin Nasser’s remarks in London and then Riyadh about expanding storage outside the Kingdom and studying additional routes for crude exports.
Inventory that has already reached beyond a disrupted route can keep serving customers through a short outage. That capability has a cost today, while its return may show up later in sales that are not lost.
Here lies the paradox: we can see the cost of the tanks, the inventory and the extra routes, but we cannot easily see the loss that might have occurred without them. These assets may support operations and the routing of sales in normal times, then grow in value when the usual route is disrupted.
We often measure efficiency by cutting inventory, raising asset utilisation and lowering costs. These are sensible goals. But relying on a single route may lower everyday costs while raising the cost of a potential disruption.
Assessing an investment therefore requires calculating what happens when the system stops, as well as what it delivers when it works. At the same time, describing spending as a boost to resilience is not enough to justify it.
The number of alternatives alone tells us nothing about the quality of the protection. We might add storage tanks without securing a way to refill them, or diversify export outlets while they remain exposed to the same source of disruption.
The practical questions are these. How likely is a disruption, how long might it last, and what loss could it cause? How many days of supply does the inventory protect, and can it be refilled if the disruption drags on?
Is the alternative route truly independent of the risks facing the original one? Only with this comparison can we estimate what the spending protects, and judge whether its cost is proportionate to the protection it provides.
There is another calculation that goes beyond the company. Continued supplies of fuel and industrial inputs protect transport, manufacturing and essential services. The economic benefit of avoiding a disruption may therefore exceed the return that appears in Aramco’s accounts alone.
That makes it essential to distinguish between the company’s return and the value of energy security when assessing an investment and deciding who should bear its cost.
For investors, these capabilities deserve scrutiny, but they do not automatically earn the company a higher valuation. What matters is how far they protect cash flows, and what the company pays for that protection.
For policymakers, the task is to estimate the impact of a disruption on the economy, then weigh the ways of limiting it. Seen from this angle, Aramco’s results become a starting point for a broader reading.
Higher prices made gains possible, but keeping them depends on decisions about operations, transport and storage, some of them taken years before the crisis. Judging those decisions on one quarter’s profits may hide their value, just as it may hide their long-term cost.
When we assess an investment in additional storage or an alternative route, do we compare its cost only with the return from using it, or do we also count the loss it could prevent?
Aramco’s Barrel Has Two Prices
Click here to read the full study
You Read It Here First in Argaam Weekend
Aramco’s Barrel Has Two Prices
Until 10 September, the East-West Pipeline was flowing at full capacity — a strategic artery carrying 7 million barrels per day from the Eastern Province to the Red Sea to bypass the Strait of Hormuz.
When Fewer Barrels Mean More Revenue
Ask most observers what a disruption to Saudi oil exports should do to the budget, and the answer comes quickly: fewer barrels, less revenue, a wider deficit.
As Saudi Arabia ramped up refined product exports, chiefly jet fuel, through its Red Sea port of Yanbu in March 2026 due to the effective closure of the Strait of Hormuz, flows surged to near-record levels — with the pipeline feeding Yanbu running at full capacity.
Saudi Oil Through Alternative Routes: An Objective Assessment of Cost and Return
The East-West Pipeline and Yanbu terminal resolve the logistics question. What they do not resolve is the fiscal one. Even with full rerouting capacity operational, Saudi Arabia faces a gap between the price its crude commands under normal conditions and the price a disrupted.